Unlock more value from your trading flow with flexible revenue sharing across spreads, swaps, commissions and P&L.

Keep 100% of Markups
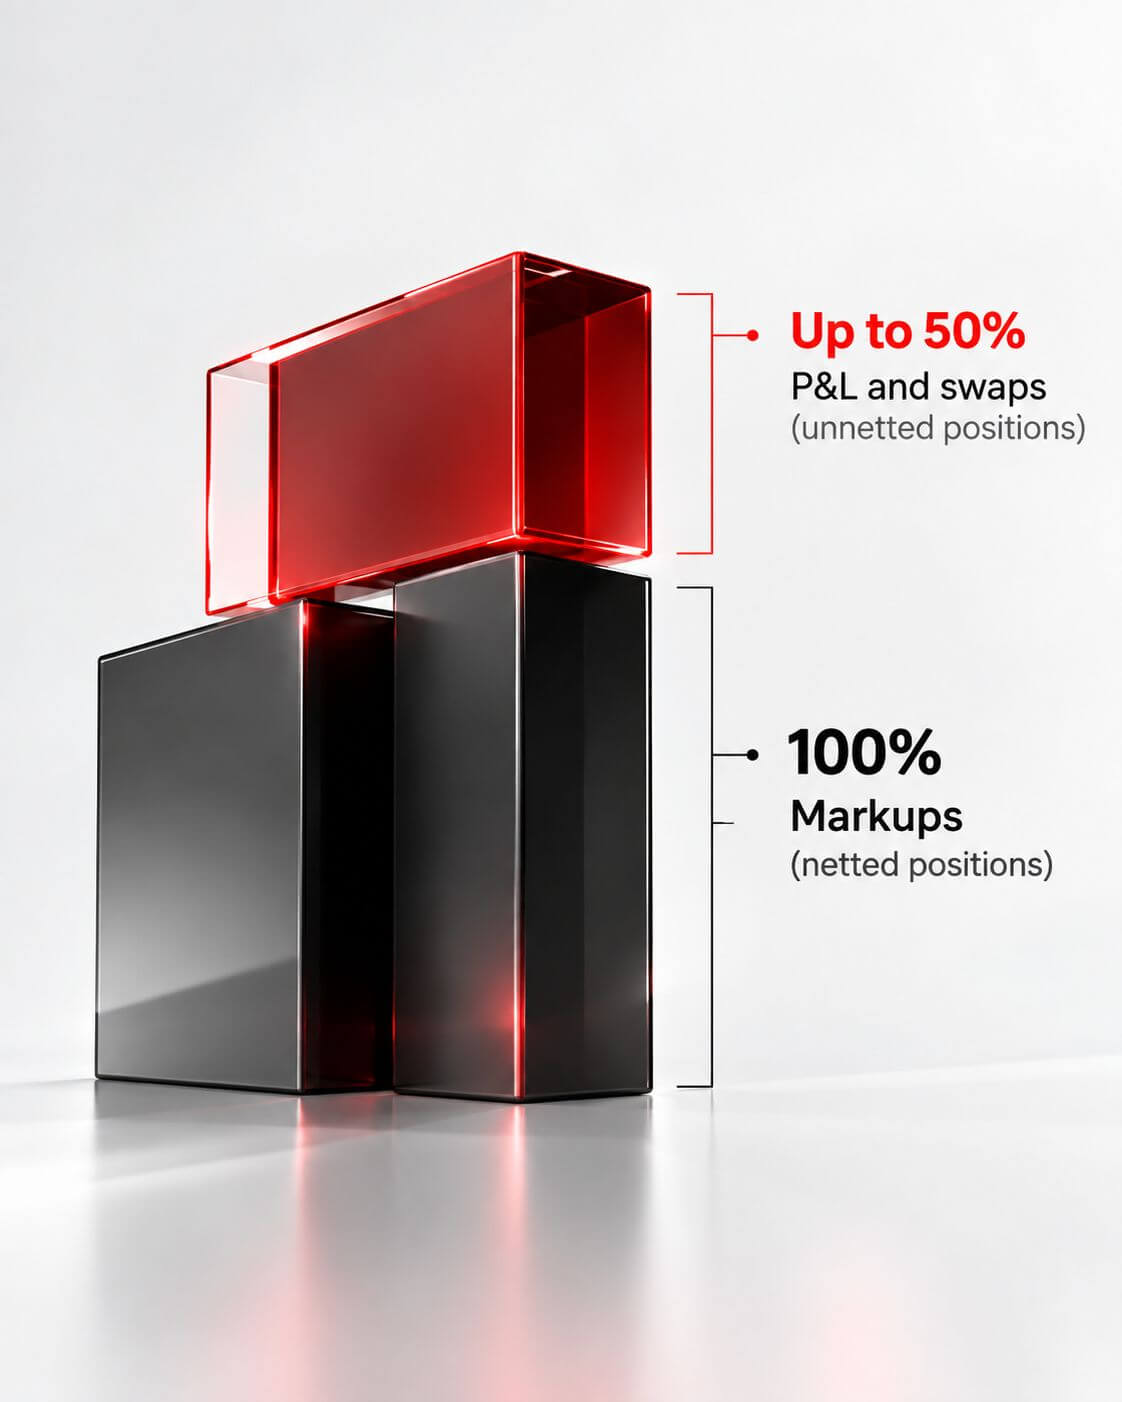
Retain 100% of spread and commission markups, as well as swaps generated from netted positions.

Up to 50% Profit Share
Share up to 50% of trading P&L and swaps generated from unnetted positions.

Built Around Your Flow
The model is structured around agreed instruments, trading volumes and risk parameters.

Clear Risk Parameters
Operate within predefined exposure and risk limits agreed for the model.

Designed for STP Brokers
Built for established STP brokers with stable trading flow and internal risk controls.

Built to Scale
Expand the model as trading volumes and your business grow.
Your flow
Client orders are executed through XTB Institutional liquidity.
Netted positions
You retain 100% of markups and swaps generated from netted positions.
Unnetted positions
You participate in up to 50% of P&L and swaps generated from unnetted positions.
Agreed risk setup
Instruments, risk parameters and commercial terms are defined based on your business needs.
Why Bookshare with XTB Institutional?
Combine a flexible Bookshare model with institutional liquidity, reliable execution and commercial terms structured around your trading flow.
Bookshare Models are flexible revenue-sharing arrangements for established STP brokers. They combine institutional liquidity with a commercial model that allows brokers to retain revenue from netted positions and participate in selected revenue generated from unnetted positions.
Client flow is assessed based on agreed instruments and risk parameters. Brokers retain 100% of eligible markups and swaps generated from netted positions and can participate in up to 50% of P&L and swaps generated from unnetted positions.
Bookshare Models are designed for established STP brokers with stable trading flow, clear internal risk controls and an established operating model.
Netted positions are positions offset within the agreed flow structure. Unnetted positions are positions that remain outside that netted exposure. The distinction determines how revenue is allocated under the Bookshare model.
Depending on the agreed model, brokers can retain 100% of eligible markups from netted positions and participate in up to 50% of P&L and swaps generated from unnetted positions. Commercial terms are agreed individually.
Yes. The structure is agreed individually based on factors such as trading flow, instruments, volumes, risk parameters and the broker’s business model.